
myFICO - Credit Score Tracking
- Rating
- 4.3
- Downloads
- 1.00M
- Content Rating
- Everyone
myFICO - Credit Score Tracking - Screenshots
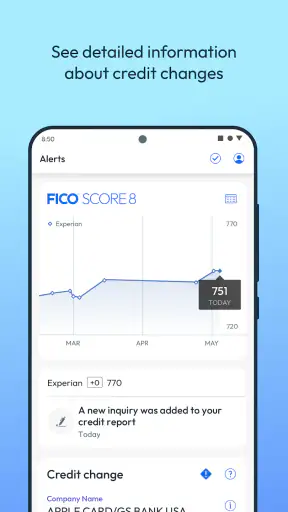
Pros
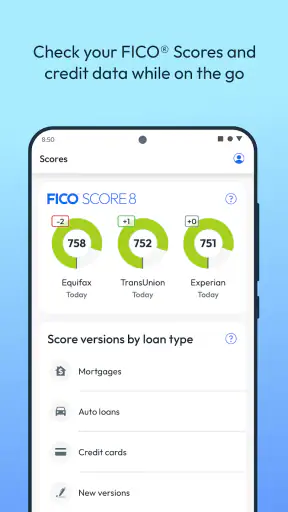
- Provides FICO Score updates from multiple credit bureaus.
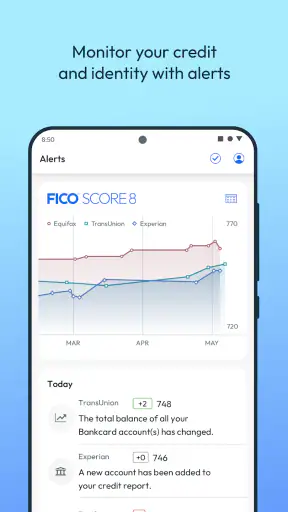
- Score history helps users monitor changes over time.
- Includes identity theft monitoring and alerts on some plans.
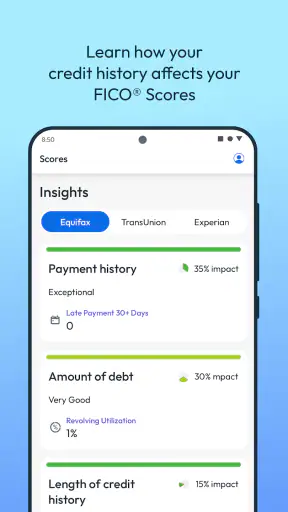
- Educational tools explain factors that influence your credit score.
- Useful calculators support loan and credit planning decisions.
Cons
- Full access to many features requires a paid subscription.
- Scores may update less frequently than your actual lender reports.
- Credit scores shown may differ from those used by some lenders.
- The app can encourage frequent checking and unnecessary credit anxiety.
- Some monitoring features require sharing sensitive financial information.
myFICO - Credit Score Tracking - Description
- App Name
- myFICO - Credit Score Tracking
- Package Name
- com.myfico
- Developer
- FICO
- Category
- Finance
- Last Updated
- Aug 18, 2015
- Version
- 4.0.23.4
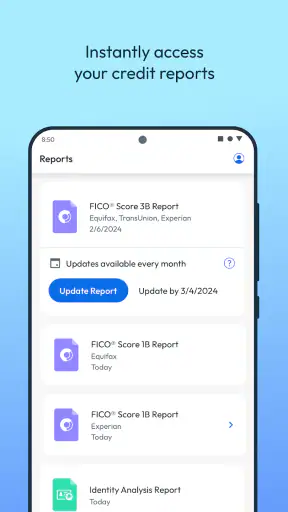
Managing credit can already feel like a chore, and it becomes even harder when the information is scattered across card accounts, loan paperwork, alerts, and different financial websites. I spent time with myFICO to see whether it makes that process easier for people with different reading, movement, attention, and day-to-day access needs. It is a finance app from FICO that focuses on viewing a FICO Score and an Equifax credit report, rather than trying to become a complete banking app.
That distinction matters. If you want one place to watch your credit information and prepare for a future credit-card, mortgage, or loan application, the app has a clear purpose. If you expect budgeting, bill payment, account aggregation, or detailed credit coaching to replace every other financial tool, you may find its scope narrow. My overall experience was that its value comes from making credit information more approachable, provided you are comfortable checking reports carefully and treating the score as a guide rather than a complete explanation of your financial health.
How myFICO handles readability, navigation, and everyday access
A focused home for credit information
The strongest part of the experience is its subject matter. Instead of presenting a broad dashboard filled with spending categories and bank balances, myFICO keeps attention on credit scoring and the Equifax report. That focus can help someone who becomes overwhelmed by crowded financial apps. When I opened it with a specific question in mind—such as whether my credit profile looked ready for a future application—the purpose was easier to understand than it would be in a general-purpose money app.
For readers who process information slowly, a focused credit app can be less tiring than switching between several websites. The useful approach is to enter with one task: inspect the score, review report details, or look for information that might need follow-up. I would not treat it as an app to browse casually for long periods. Credit reports contain unfamiliar terms, and reading every section without a plan can become mentally demanding.
The app is free to install, which lowers the barrier for someone who wants to explore the basic experience before deciding whether it belongs in a regular financial routine. The age rating is Everyone, so its presentation is intended for a broad audience. That does not make credit terminology automatically simple, however. A reader may still need time to understand accounts, inquiries, payment history, and other parts of a report.
Useful habits for clearer reading
I found that the app works best when I separate “what the score is” from “why the score looks that way.” A score gives a quick snapshot, while the report provides the underlying account information. Looking only at the number can encourage unnecessary worry, especially when a small movement seems important. Reading the report afterward gives the number context and makes the review more practical.
My advice is to keep a short note outside the app with three headings: information I recognize, information I need to investigate, and information I should monitor later. This simple workflow is more useful than repeatedly refreshing the score. It also helps people who have memory difficulties or attention limitations because the next action is written down rather than held in mind.
Another helpful habit is to review the report when you are rested, not while rushing through a purchase or loan application. Credit information is detail-heavy. If text or financial terminology is difficult to absorb, a calm review with a trusted person can be more effective than trying to solve everything in one sitting. The app can present the information, but it cannot replace your judgment about whether an entry is correct or what action to take.
Navigation for different reading and attention styles
People who prefer a single, prominent task may appreciate the app’s narrow purpose. People who need extensive explanations, visual summaries, or step-by-step education may want to supplement it with official educational material or a separate credit-learning resource. I would not assume that a score display alone teaches a new user how credit works.
For users with dyslexia, cognitive fatigue, or limited financial experience, the most important accessibility question is not simply whether the screen looks tidy. It is whether the wording can be understood without guessing. Credit products often use terms that sound familiar but have precise meanings. I recommend pausing over unfamiliar labels and checking the report details instead of making a decision from a headline number.
For users who rely on larger text or a screen reader, the practical experience will also depend on the phone’s operating-system settings and how each screen exposes its content. I would test the main score view and report sections early, before relying on the app for an urgent application. That is a sensible step with any finance app because a person needs to know whether key information remains understandable with their preferred display or audio settings.
Motor and sensory considerations
Credit monitoring is a good example of a task that can be completed in short sessions. Someone with limited stamina, hand movement, or concentration does not need to stay in the app for a long period. A focused visit can involve opening the score, checking the report, and recording a follow-up question. That makes the product more manageable than a financial tool that expects frequent data entry or complicated planning.
At the same time, credit review is not entirely passive. Reading a report can require scrolling, selecting sections, comparing details, and returning to earlier information. For someone with tremors, reduced dexterity, or difficulty with precise touch gestures, those transitions may be frustrating. I would use the phone’s built-in touch accommodations, larger interface settings, or voice-control tools where available, then confirm that the important report content is still easy to reach.
Visual sensitivity is another consideration. Financial screens can become stressful when a user feels pressured by a changing number or warning-like language. I found it more comfortable to treat the score as information rather than a judgment. If you are sensitive to visual clutter or numerical emphasis, open the app with a written purpose and avoid turning every change into an emergency.
For users with hearing loss, the core activity is naturally visual, so the app’s main purpose does not depend on listening to a conversation or phone call. For users with low vision, the more important test is whether the score and report text can be enlarged and navigated reliably. I would not make a major borrowing decision until I had confirmed that the relevant details were accessible in the way I personally read.
A realistic everyday scenario
Imagine that I am considering applying for a mortgage later this year. I would not open myFICO only on the day I speak with a lender. Instead, I would check the score and Equifax report during a quiet weekly or monthly review, note accounts or inquiries I do not immediately recognize, and keep a record of questions for the lender or creditor. If something looks wrong, I would investigate it before the application becomes urgent.
This workflow is especially useful for someone who has difficulty managing several deadlines at once. The app becomes a checkpoint rather than a source of last-minute panic. A family member or support person could help read the report, while I retain control over what I want to ask and what action I want to take.
The same approach works for a planned credit-card application or loan comparison. I would use the app to understand my current position, but I would not assume that the displayed score guarantees approval, a particular interest rate, or a specific lending decision. Those outcomes depend on the lender and the full application, so the app should inform preparation rather than promise a result.
Situational access when life is busy
myFICO is most helpful when access to a larger screen or desktop website is inconvenient. A phone-based review can fit into a quiet moment at home, during a break, or while organizing paperwork. That convenience matters for caregivers, shift workers, people who travel, and anyone whose schedule makes a long financial session difficult.
However, mobile access is not automatically equal access. A person may be using a small screen in bright sunlight, on a weak connection, with one hand occupied, or while dealing with stress. Those conditions can make a detailed credit report harder to read. I would avoid checking sensitive financial information in a crowded public place, not because the app is unsuitable there, but because privacy and concentration are both important.
For someone sharing a device with family members, the app also requires a little planning. Credit information is personal. I would use the device’s normal security protections, avoid leaving the report open, and sign out or lock the phone according to my own security habits. These are ordinary precautions, but they become more important when another person helps with reading or navigation.
The app’s one-million-plus installs and average rating of 4.3 from around twelve thousand ratings suggest that it has reached a substantial audience and is generally well received. I see that as useful context, not proof that every user will find it accessible. A person’s experience can differ considerably depending on vision, motor control, reading style, phone settings, and familiarity with credit language.
Where the app may not be the right choice
The clearest limitation is scope. myFICO is not the tool I would choose for tracking household spending, creating a detailed budget, paying bills, or viewing every financial account in one place. A budgeting app may be better for someone whose main goal is controlling cash flow. A lender’s own tools may be more relevant when the immediate task is managing an existing loan. The right alternative depends on whether the problem is credit understanding, daily money management, or borrowing administration.
I also would not recommend relying on it as the only source of financial education. A score can be easy to notice but difficult to interpret. Someone new to credit may need plain-language explanations of how payment history, balances, account age, and applications affect a profile. The app can be part of that learning process, but it should not encourage a user to reduce a complicated report to one number.
Another trade-off is emotional. People who are prone to checking financial information repeatedly may find credit monitoring reassuring at first but stressful over time. I would set a review routine instead of opening the app whenever I feel uncertain. That makes the information serve a decision rather than control the day.
Version, platform expectations, and practical preparation
The current version is 4.0.23.4, and the app requires at least iOS or Android version 12. Before installing, I would check the operating system on the phone, particularly if it is an older device used with accessibility settings or assistive tools. Updating an operating system can sometimes change text scaling, navigation gestures, or screen-reader behavior, so I would test the app again after a major device update.
Because this is a finance app, I would also prepare before the first serious review. Have any relevant account paperwork nearby, use a private setting, and allow enough time to read rather than tapping through quickly. If another person is assisting, decide in advance whether they are helping with navigation, explaining terminology, or simply taking notes. Clear roles reduce the risk of sharing more personal information than necessary.
FICO is the developer, and the product’s identity is closely tied to the FICO Score. That can be valuable for users who specifically want to follow this type of score, but it also means I would pay attention to which score or report information I am viewing and how it relates to the lender or decision I care about. A credit score is not a universal pass-or-fail label, and comparing different financial contexts requires care.
Remaining barriers and ways to reduce friction
The biggest barrier is not installation; it is interpretation. A person may be able to open the app easily and still struggle to decide whether a report entry matters. I would reduce that friction by reviewing one section at a time, writing down exact questions, and asking a trusted support person to help with reading rather than asking them to make the financial decision.
Another barrier is the risk of confusing monitoring with correction. Seeing an unfamiliar item is only the beginning of an investigation. I would preserve the relevant details, compare them with personal records, and contact the appropriate organization through a trusted channel before taking action. The app can help me notice something, but I would not treat the screen itself as a complete dispute process.
People with limited English proficiency may also need extra support with terminology. I would prefer a human explanation or reliable educational material over guessing from a translated phrase. Financial misunderstandings can be costly, so accessibility here includes language clarity, patience, and the ability to ask questions.
There is also a practical barrier for people who cannot comfortably use a smartphone. If touch navigation, small text, or authentication steps are difficult, a larger-screen alternative or assistance from a trusted person may be better. I would not choose an app simply because it is mobile if the phone format makes the task less independent.
My inclusive verdict
I see myFICO as a useful, focused option for checking a FICO Score and reviewing an Equifax credit report from a phone. Its free price makes trying it straightforward, and its Everyone rating gives it broad appeal. The reach of more than one million installs and a 4.3 average from thousands of ratings also suggests that many people find the product worthwhile, although those figures cannot predict how well it will fit a particular accessibility need.
For me, the app is at its best when used deliberately: one credit question at a time, with notes, privacy, and enough time to read. It can support someone preparing for a card, mortgage, or loan, especially when a short mobile session is easier than organizing a larger financial system. It is also a reasonable companion for a support person helping with navigation or report reading, as long as the account owner remains in control of personal decisions.
I would skip it if I wanted a complete budgeting center, if I needed extensive built-in financial lessons, or if the phone’s display and touch controls made detailed reading uncomfortable. In those cases, a larger-screen service, a budgeting tool, or direct guidance from a qualified financial professional may be more suitable.
My recommendation is to use myFICO as a credit-awareness tool, not as a verdict on your financial life. Its focused design can make an important task less scattered, but inclusive access depends on how well the text, controls, device settings, and support arrangement work for you. Used with that realistic expectation, it gives many people a practical way to prepare, notice questions early, and approach credit decisions with more confidence.
FAQ
What is myFICO - Credit Score Tracking used for?
myFICO - Credit Score Tracking is designed to help users monitor their FICO credit scores, review credit-report information, and better understand the factors influencing their credit profile. After signing in, the app presents score details and available monitoring information in a more convenient format than regularly visiting the website. It is mainly useful for people preparing for major financial decisions, such as applying for a loan, credit card, or mortgage.
Does the myFICO app provide the same credit score that lenders use?
The app focuses on FICO Scores, which are widely used by lenders, but the exact score available to you can depend on your subscription, score version, and the credit bureau data included with your plan. Not every lender uses the same FICO model or bureau report. Therefore, the score shown in the app can be a helpful reference, but it should not be treated as a guarantee that a lender will see precisely the same number.
Is myFICO - Credit Score Tracking free to use?
Downloading the app may be free, but access to many of its most valuable features generally depends on a myFICO membership or an eligible paid plan. Subscription options can include different levels of score access, credit-report monitoring, alerts, and update frequency. Before starting a trial or subscription, review the current pricing, renewal terms, included features, and cancellation policy in the app store or on the official myFICO website.
How often are credit scores and reports updated in the app?
Update frequency depends on the myFICO plan you choose and on when lenders send new information to the credit bureaus. Credit reports do not change every time a payment is made, and a recent account activity may take time to appear. The app can help you track available updates and alerts, but it cannot force a bureau or lender to refresh information immediately.
Is my personal and financial information secure in myFICO?
Because myFICO handles sensitive credit and identity information, users should sign in only through the official app and keep the application updated. Use a strong, unique password and enable any available security or verification options. The app may require personal details to verify your identity and connect you with credit-report data. Even with security protections in place, avoid sharing login credentials and review alerts promptly for unfamiliar activity.


